IZA@LISER Network
| October 1, 2026
Economists have long argued that anomalous behavior can be safely ignored in markets, because competition will discipline it: competition punishes firms that make bad decisions and eventually pushes them out.
The textbook illustration of this claim comes from a seminal 2003 study by John List, which showed that while casual sports memorabilia buyers exhibited behavioral anomalies, professional traders did not. However, direct evidence on whether these anomalies fade as markets themselves become more competitive is far scarcer.
A recent IZA discussion paper by David Huffman, Lamar Pierce, Alex Rees-Jones and Germán Reyes revisits this old question in a large, high-stakes setting: the U.S. dealer network of a major auto manufacturer.
Context: U.S. car dealerships
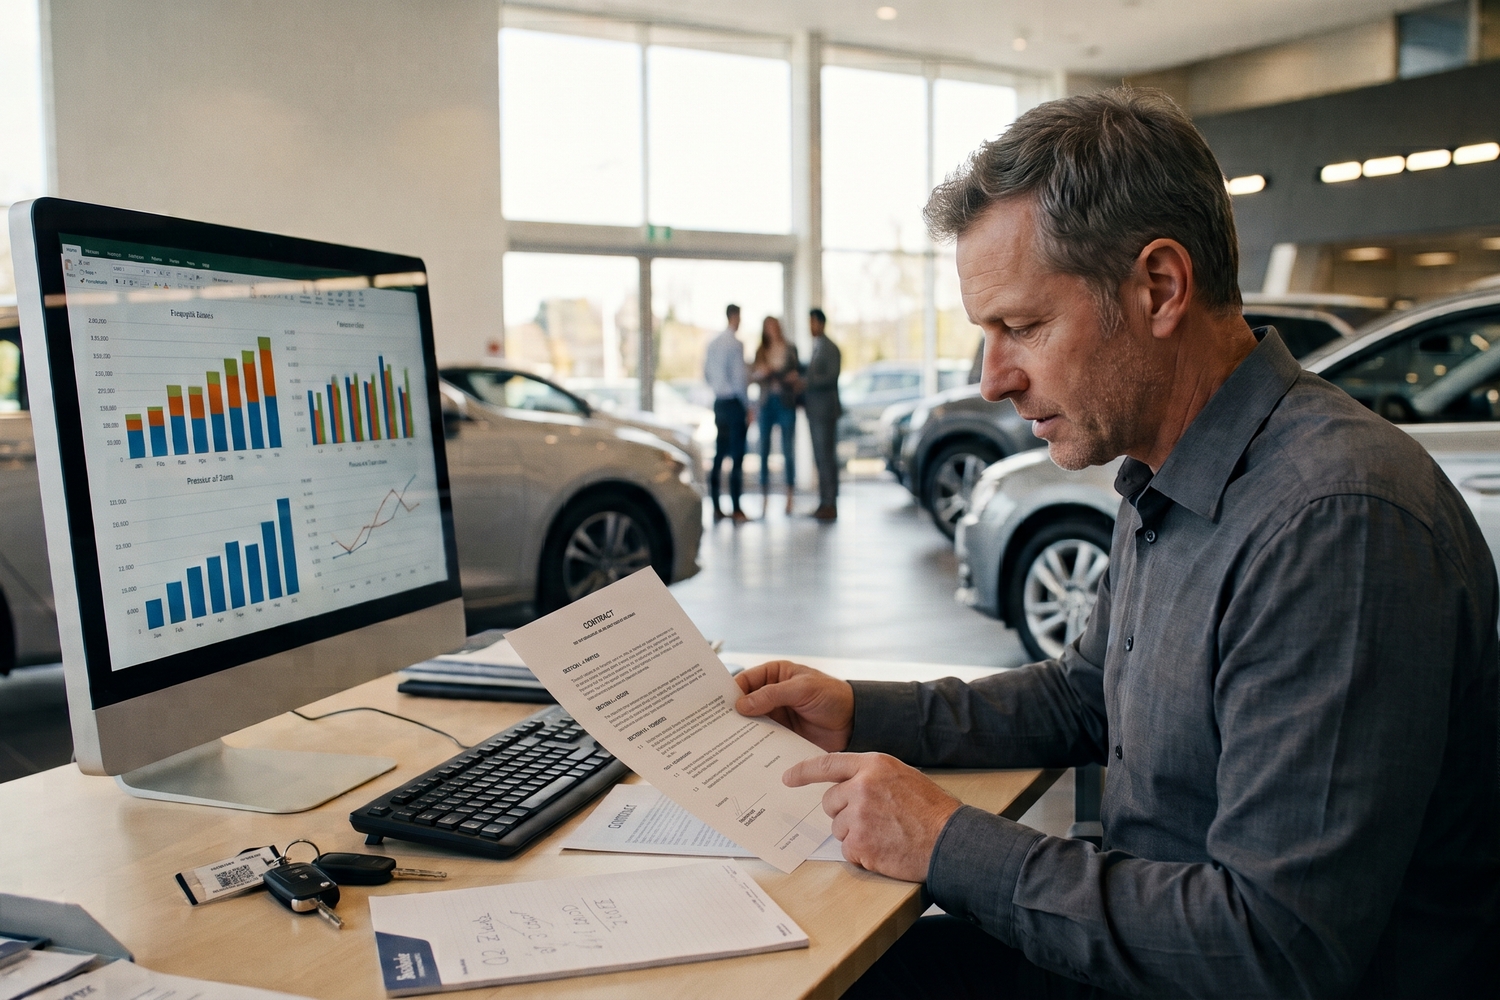
In the U.S., state franchise laws bar auto manufacturers from selling directly to consumers. Cars must be sold through independent dealerships, which buy vehicles at fixed invoice prices and set retail prices on their own. Volume-based bonus programs are the manufacturer’s main lever over dealer behavior, typically accounting for 15 to 20 percent of a dealership’s gross profits.
Between 2017 and 2019, the manufacturer in the study let dealers choose between two bonus contracts rewarding monthly sales. These were worth nearly $300,000 a year on average. This makes an anomaly easy to identify: a dealer errs by picking the contract that, after the fact, pays less than the alternative would have—a non-profit-maximizing choice.
Anomalies turn out to be common and expensive. In 20% of dealer-years, dealers chose the contract that left money on the table. The average mistake cost about $18,000 in forgone profit per year—and nearly $58,000 for the costliest tenth of cases.
Competition halves mistakes
Crucially, dealers face very different competitive environments. Some sit in tightly contested metro areas, while others are effectively local monopolies.
By tracking these differences, the paper shows that mistakes clearly climb with market concentration. The authors’ estimates imply a mistake rate of 34% under monopoly versus 16% under perfect competition: competition roughly halves mistakes, but does not entirely eliminate them.
Improvement or selection?
But why does competition impose discipline? One classic story is selection: a firm that persistently leaves money on the table falls below the break-even threshold and is eventually forced out. The market improves as bad decision-makers disappear.
That is not what drives the results. When the authors restrict attention to dealers that survive the entire study period—so that exit plays no role—their estimates barely move. Competition acts on the same firms, leading them to make better choices, rather than culling the ones that don’t.
The authors’ leading conjecture is inattention: competitive pressure may serve as a wake-up call that prompts more careful, data-based forecasting.
Download the full paper here.